Inflation in the United States has once again become a global concern. The latest data from the U.S. Bureau of Labor Statistics show that price pressures in the world's largest economy have yet to ease. The Consumer Price Index (CPI) rose by 0.6 percent month-on-month in September 2026 and by 3.7 percent compared with September of the previous year, up from 3.4 percent in August. This figure remains well above the Federal Reserve's 2 percent inflation target.
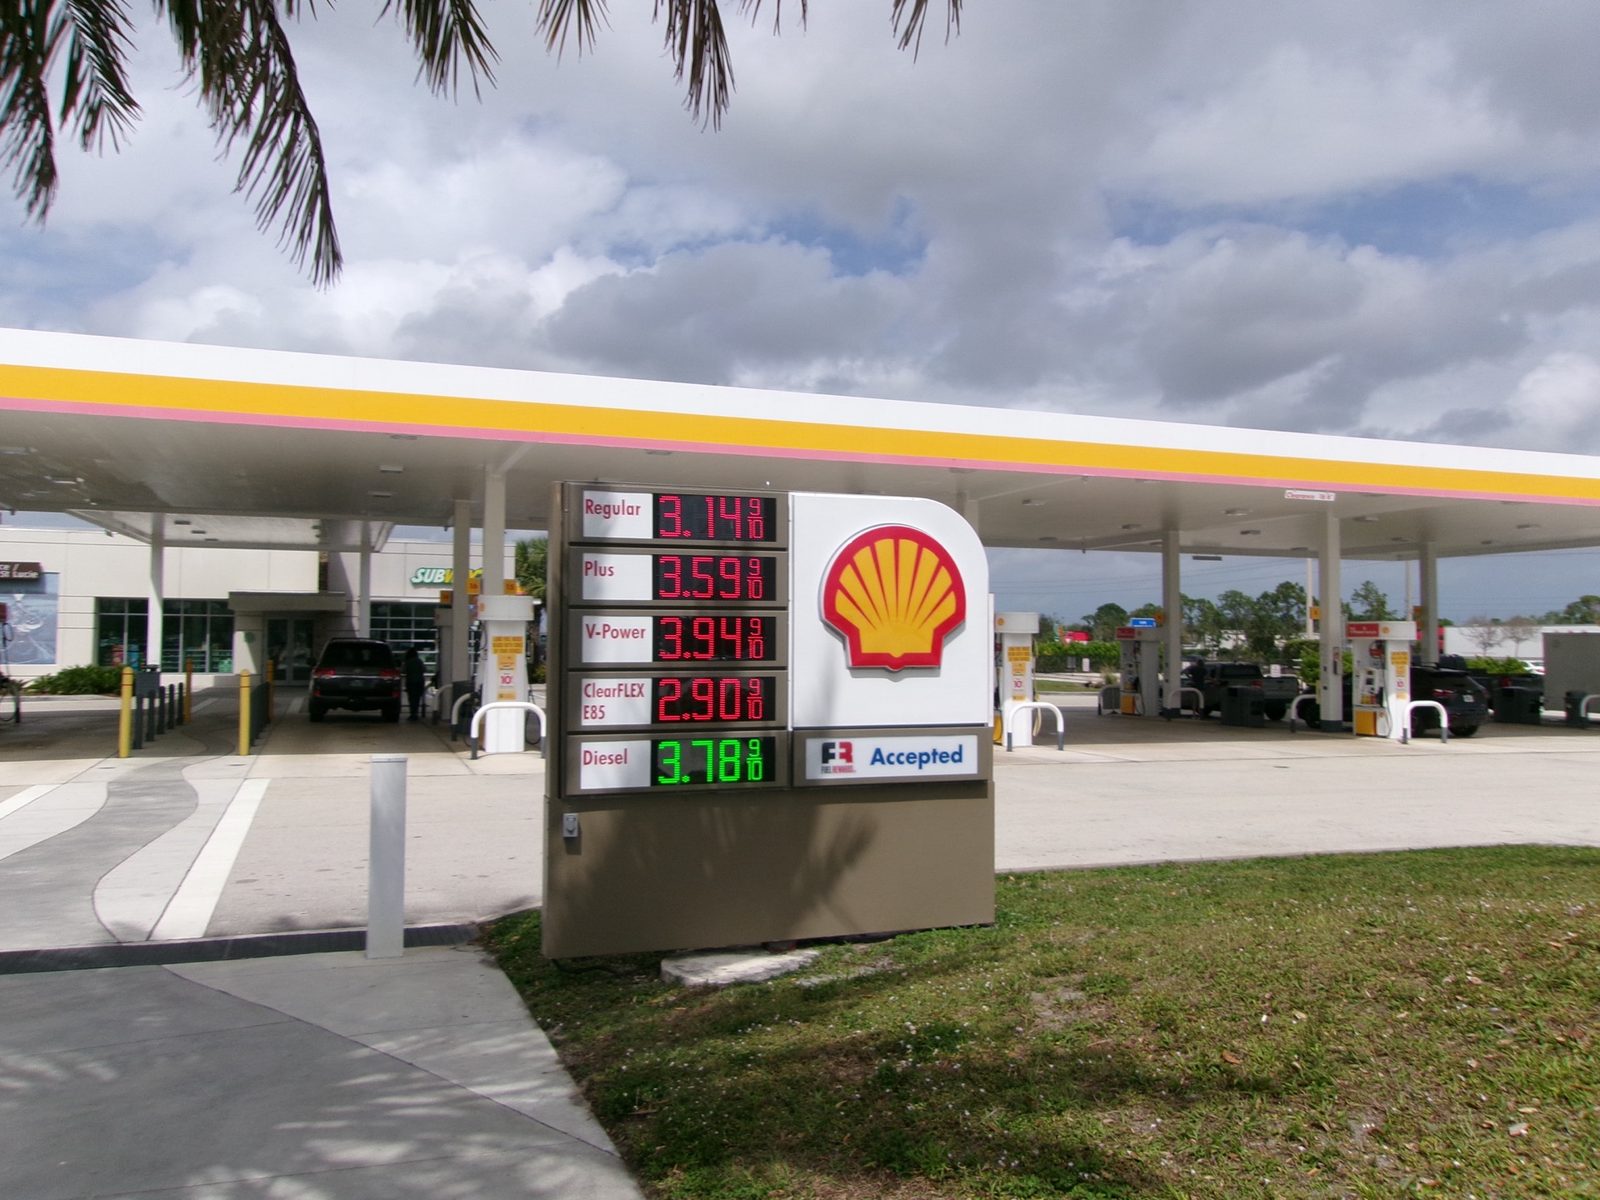
The situation is more concerning because price increases are not confined to just one or two commodities. Energy prices surged by 5.2 percent in a single month and increased by 20.4 percent year-on-year. Gasoline prices rose by 9.1 percent in September and by 34.2 percent compared with the same period last year. Fuel oil prices surged by as much as 74.2 percent year-on-year. Meanwhile, food prices remained relatively stable, increasing by 2.5 percent over the year.
Beyond food and energy, core inflation is also showing signs of pressure. Core CPI rose by 0.3 percent month-on-month and 2.6 percent year-on-year. Shelter costs continued to increase by 3.2 percent annually, while airfares surged by 22.4 percent. Education costs rose by 3.8 percent, and healthcare costs also continued to increase. This means that US inflation can no longer be regarded solely as an oil-price problem.
The main driver of the latest inflation surge is energy. Geopolitical tensions in the Middle East have increased the risk of energy supply disruptions and higher transportation costs. Rising fuel prices subsequently feed into logistics, distribution, manufacturing, aviation, and ultimately the prices consumers pay for goods.
However, other factors are equally important. Massive investments in artificial intelligence (AI) are increasing demand for semiconductors, technological equipment, data centres, electricity, and infrastructure. Meanwhile, trade policies and tariffs are also raising the cost of certain imported goods. As a result, US inflation is now being driven by a combination of energy shocks, geopolitics, supply-chain disruptions, and demand-side pressures. Reuters has noted that price pressures are beginning to spread beyond energy, raising concerns that inflation could become more persistent.
When Income Fails to Keep Pace with Prices
The greatest challenge facing households is not simply the 3.7 percent inflation rate, but its impact on real income. Data from the BLS show that real average hourly earnings, or average hourly earnings adjusted for inflation, fell by 0.7 percent year-on-year in September 2026. Real average weekly earnings also declined by 0.1 percent over the same period.
This means that some workers are facing a situation in which nominal wages may still be increasing, but their ability to purchase goods and services is actually declining. The impact is more severe for low- and middle-income groups because a relatively large share of their income goes towards food, energy, housing, and transportation.
This phenomenon is also reflected in consumer sentiment. The Conference Board's Consumer Confidence Index fell by 6.7 points to 81.9 in September, a very low level that reflects growing household concerns about inflation and energy costs.
Interestingly, retail sales continue to demonstrate resilience. In August, US retail sales surged by 1.2 percent month-on-month, while core retail sales increased by 1.4 percent. However, strong sales do not automatically mean that household purchasing power is becoming healthier. Some consumption is still supported by financial wealth, savings, and the depletion of household savings. Reuters has reported that consumers are also becoming more selective and increasingly seeking lower-priced goods.
This reveals a paradox in the US economy: the economy is still capable of growing and consumption remains strong, but the quality of household purchasing power is beginning to deteriorate.
An Alarm for the Global Economy
The problem of US inflation does not stop at America's borders. The United States remains at the centre of the global financial system, while the dollar continues to serve as the principal currency for international trade, investment, and foreign exchange reserves.
If inflation remains high, the Federal Reserve will have less room to cut interest rates. The possibility of further rate increases could even re-emerge. At the same time, Treasury yields may remain elevated, and the dollar could face upward pressure against other currencies.
Editor's note: The Federal Reserve had already raised its target range for the federal funds rate by a quarter of a percentage point on 16 September 2026, to 3.75 to 4 per cent, its first increase since 2023.
The consequences can be felt in emerging economies through capital flows, exchange rates, financing costs, and commodity prices. Countries with dollar-denominated debt may face heavier debt burdens when the dollar strengthens.
This is where US inflation becomes more than a domestic issue. It becomes an indicator that the global economy is undergoing structural change. As a major player in the global economy, does this paradox in the US economy signal that the world is moving towards a new economic order? The answer may not lie in a complete transformation of the existing system, but rather in increasingly pronounced fragmentation. Global trade is becoming more heavily influenced by geopolitics. Supply chains are being diversified. Countries are seeking alternative sources of energy, technology, markets, and payment systems.
This phenomenon does not mean that the dollar will soon lose its dominance. On the contrary, inflationary pressures and US monetary policy demonstrate just how influential America remains in the global economy.
Nevertheless, countries are beginning to recognise that excessive dependence on a single economic centre carries risks. Consequently, trade diversification, the use of local currencies, stronger domestic markets, and regional cooperation will become increasingly important.
The Road Ahead
Going forward, the United States needs to maintain the credibility of its monetary policy while addressing the supply-side sources of inflation. Energy stability, supply-chain efficiency, and productivity improvements must go hand in hand with interest-rate policy.
For other countries, this phenomenon offers a clear lesson: economic growth should not rely solely on consumption driven by the global economy. Countries need to strengthen food and energy security, expand trade among developing economies, promote local currencies in bilateral transactions, and develop domestic markets.
For Asian countries, this moment should be viewed as an opportunity. As the global economy begins searching for a new configuration, Asia must not remain merely a market. It must become one of the world's centres of production, trade, technology, finance, and economic growth.
US inflation reaching 3.7 percent is not merely a statistic. It signals that the cost of maintaining the existing economic order is becoming increasingly high. The world may not yet be abandoning the economic system built around the United States, but efforts to find a new equilibrium must continue in pursuit of a more balanced and equitable global economic order.
Comments
No comments yet. Be the first.
Comments are closed on this article.