Protests in various European countries show that economic stability cannot be measured solely through gross domestic product (GDP) growth, inflation, or financial market performance. Behind these macroeconomic indicators lie more fundamental issues: the ability of people to maintain purchasing power, obtain affordable housing, and access public services. When growth does not result in evenly shared improvements in perceived welfare, social pressures can develop into structural risks for the economy.
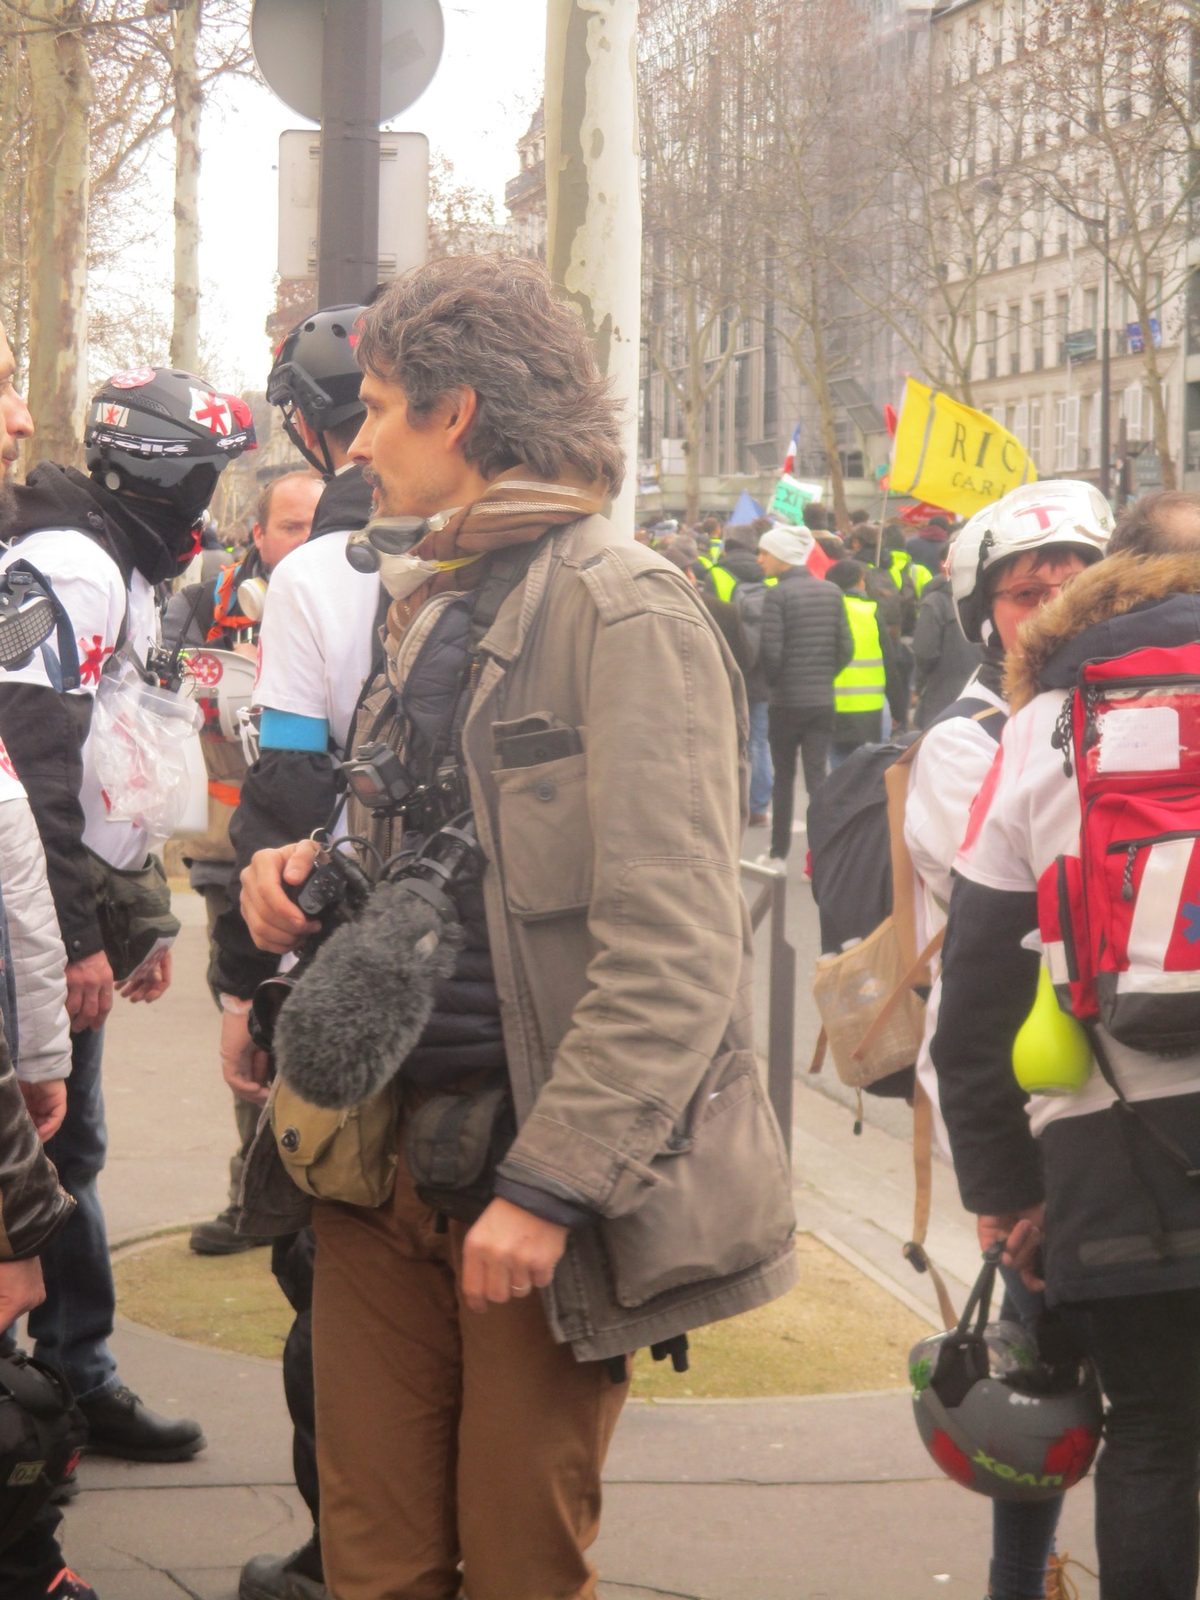
In October 2026, protests and social tensions took place in several European countries, including France, Italy, Spain, Portugal, and Belgium. Albania also faced unrest stemming from its own political circumstances. Although the demands in each country differed, the cost of living, housing, wages, education, and the quality of public services were important elements of public dissatisfaction. A Euronews report dated October 19, 2026, described how these pressures developed into demonstrations in various cities.
One indicator that deserves attention is the price of food and non-alcoholic beverages in the European Union, which increased by around 34% between August 2021 and August 2026. In Malta, Spain, and France, the ability of gross minimum wages to purchase food also declined during this period. These data show that slowing inflation does not automatically restore purchasing power: prices that have already risen substantially continue to burden households.
These problems are compounded by expensive housing and pressure on public services. For low-income groups, rising rental, energy, and food costs reduce the room available for other consumption. Thus, protests are not merely a matter of public order, but a signal that some segments of society are facing increasingly difficult economic pressures.
From Social Dissatisfaction to Structural Risk
In economic theory, the first mechanism can be explained through the concept of real purchasing power. When the prices of basic necessities rise faster than income, households will reduce non-essential consumption. If this occurs broadly, declining demand can put pressure on company sales, production, investment, and labor recruitment.
The second mechanism concerns inequality in the distribution of the benefits of growth. The economy may grow and asset values may increase, but the benefits are not always distributed evenly. Property owners gain from rising house prices, while young workers face increasingly expensive rents. Dissatisfaction arises not only from absolute poverty, but also from the gap between actual living conditions and people's expectations. This phenomenon is related to the theory of relative deprivation.
Structural risks emerge when these two problems meet policy uncertainty. Prolonged demonstrations, strikes, and transport disruptions can increase business costs and delay production activities. If companies believe that uncertainty will persist for a long time, investment decisions may be postponed. The subsequent decline in investment can potentially slow productivity growth and job creation.
However, it is important to distinguish protests as a cause of economic losses from protests as a symptom of economic weaknesses that were already present. The two can reinforce each other, but they do not always have the same causal relationship.
Empirical Lessons from France
The experience of the Yellow Vests movement in France in 2018 provides a concrete example. The movement began with opposition to a planned increase in fuel taxes, then developed into protests against the cost of living, the tax burden, and the direction of government reforms.
In its 2019 French economic consultation report, the International Monetary Fund (IMF) estimated that unrest related to the movement disrupted retail sales and consumption, with a negative impact of around 0.1 percentage point on output growth in the fourth quarter of 2018 and the first quarter of 2019. The government subsequently canceled the planned fuel tax increase and took a number of measures to increase household disposable income. The response illustrated a policy dilemma: governments need to maintain the reform agenda, but must also take into account society's ability to bear the costs of adjustment.
Broader evidence is also available in IMF research on the macroeconomic impact of social unrest. The research found that social unrest can depress consumption, manufacturing, and services, while also increasing uncertainty and reducing confidence. The magnitude of the impact depends on the nature of the unrest, initial economic conditions, institutional strength, and the government's policy space.
Preventing Risks Before They Become a Crisis
Governments need to respond to these issues through policies that address their root causes. This can be done through the following approaches:
First, increasing productivity and real incomes so that economic growth is more strongly felt at the household level.
Second, expanding the supply of affordable housing and improving access to transportation, education, and healthcare services.
Third, social assistance and subsidies should be directed toward the most vulnerable groups, accompanied by sustainable fiscal financing. Assistance that is too broad can burden the budget, while excessively rapid fiscal consolidation risks depressing demand and increasing dissatisfaction.
Fourth, dialogue between governments, workers, businesses, and society needs to take place before major reforms are implemented.
Thus, protests in Europe are a reminder that macroeconomic stability is not always synonymous with social stability. Structural risks become serious when purchasing power weakens, investment is delayed, productivity stagnates, and governments' fiscal space narrows simultaneously.
Sustainable growth is not only a matter of how much the economy expands, but also how its benefits are distributed and experienced by society. If these imbalances continue to be ignored, cost-of-living pressures that initially appear sectoral can develop into a crisis of confidence, hamper investment, and weaken the foundations of long-term growth.
Comments
No comments yet. Be the first.
Comments are closed on this article.