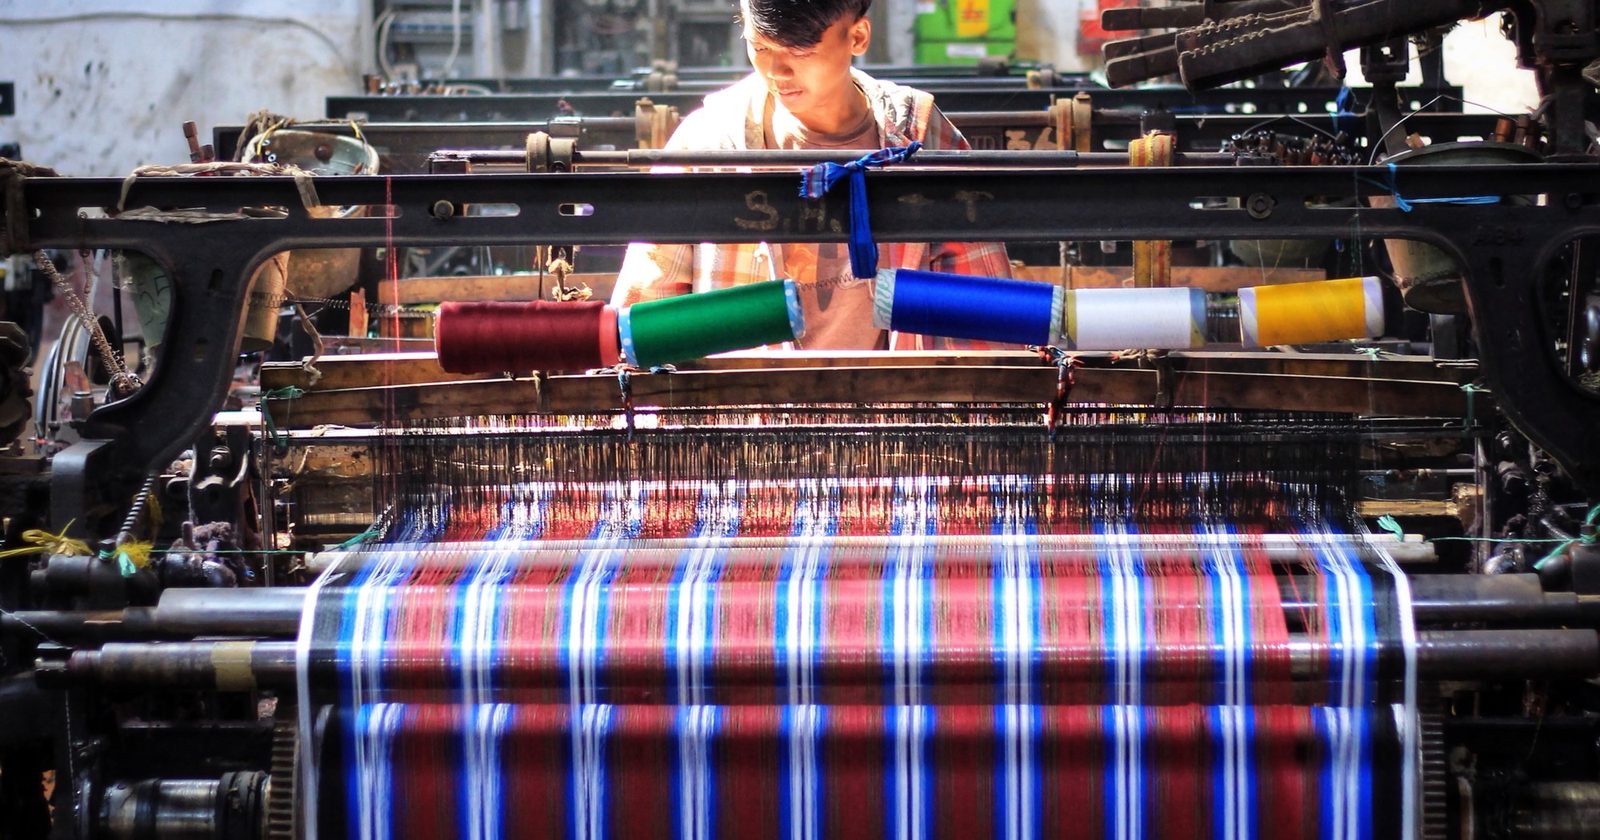
Imagine a small business owner who receives additional financing to purchase new production equipment. His production capacity doubles, but the number of customers remains unchanged. The machine that was expected to generate more income instead becomes an additional financial burden. Capital is available, but the promised growth does not necessarily follow.
This simple example reminds us that financing is not the ultimate objective of economic development. It is a means to create productive economic activity. The success of Islamic finance, therefore, should not be measured solely by the amount of financing disbursed or the value of business agreements announced, but by the economic benefits it actually generates.
Indonesia’s Sharia Economic Festival (ISEF) 2026 illustrates both the scale of the opportunity and the importance of this distinction. During a business agreement ceremony on October 16, 2026, various consolidated agreements reached approximately Rp27.43 trillion. Meanwhile, Islamic banking financing had grown by 11.61 percent year-on-year to Rp748.7 trillion as of August 2026, while the gross non-performing financing ratio stood at 2.3 percent.
These figures point to an industry that continues to expand. Yet one question deserves greater attention: to what extent is the growth of Islamic finance actually strengthening productive businesses and improving economic welfare?
Growth Is More Than Financing
In finance, the amount of money disbursed is relatively easy to measure. Its impact is much harder to quantify. Financing provided to a business does not automatically translate into higher productivity, particularly when entrepreneurs lack market access, management capabilities, or adequate business planning.
Consider the analogy of building a road. The number of kilometres constructed may represent a physical achievement, but the road’s real value emerges only when it connects people to schools, markets, jobs and public services. Financing should be viewed in much the same way. Its value lies in the economic activity it enables.
Indonesia has considerable potential to develop its halal industries. The State of the Global Islamic Economy 2025/2026 report ranked Indonesia fourth in the global Islamic economy ecosystem, with strong positions in sectors including modest fashion and halal food.
This creates significant opportunities for local businesses. Yet a strong international ranking does not automatically enable every small producer to increase sales or enter larger markets.
What is needed is a stronger bridge connecting capital, production capacity, quality standards and consumer demand. Without such connections, the financial side of the Islamic economy risks expanding faster than the productive businesses it is supposed to support.
Finance Cannot Solve Everything
One could reasonably argue that the role of financial institutions is to provide financing, not to guarantee the success of every business they fund. This argument is valid to a certain extent. Business risks will always exist, and financial institutions must maintain prudent financing standards to protect public funds.
But prudence does not mean assessing financing applications solely through administrative requirements and conventional indicators of repayment capacity.
Understanding the characteristics of a business, its revenue cycle, working-capital requirements and market prospects can help financial institutions provide financing more effectively.
This is where stronger links between finance and the real economy become important. Initiatives that connect access to capital with access to markets can help match businesses with appropriate sources of financing. Assistance with financial record-keeping, product quality and marketing can also strengthen entrepreneurs’ ability to manage the funds they receive.
Such an approach will not guarantee that every business succeeds. Markets change, competition intensifies and failures will still occur. That is precisely why evaluation and risk management should be integrated into the financing process rather than introduced only after problems emerge.
Measuring What Actually Changes
The Rp27.43 trillion in business agreements announced during ISEF 2026 should also be interpreted carefully. It represents a consolidation of various commitments rather than evidence that the entire amount has already translated into completed transactions and measurable economic impact.
The same announcement recorded Letters of Intent for trade cooperation between micro, small and medium-sized enterprises and buyers worth approximately Rp9.78 billion. The distinction between commitments, realization and eventual economic outcomes matters if Islamic finance is to be evaluated objectively.
Going forward, the performance of Islamic finance should therefore be assessed beyond the amount of money disbursed.
Did businesses increase their production capacity? Did their sales improve? Were they able to retain or create jobs while meeting their financial obligations? Did they gain access to wider markets?
These questions provide a more meaningful way to evaluate impact without assuming that every financing arrangement will inevitably succeed.
Islamic finance has the potential to become a powerful driver of more inclusive economic growth, particularly in emerging economies where many productive businesses still face difficulties accessing capital and markets. But that potential will only be realized if the expansion of financial services is accompanied by stronger businesses in the real economy.
Ultimately, success should not be measured simply by how much money changes hands, but by how much productive economic activity becomes stronger because of it.
Transaction figures can mark the beginning of a story. Only tangible economic impact can prove that the story has led to meaningful change.
Comments
No comments yet. Be the first.
Comments are closed on this article.