On January 10, 2027, Beijing must decide whether to extend, narrow, or reimpose the rare-earth export controls, which it suspended last year. The choices are not simple; they expose a bigger problem for Beijing. Since its first deliberate use of critical minerals as economic coercion in 2010, China has orchestrated export bans on various occasions. It first used them against Japan, then against Washington in 2023, 2024, and 2025, and each time it worked, even if only briefly. But every use by Beijing has pushed Washington and its allies to seek alternatives, and the consequent efforts now continue whether China acts or not.
The famous use-it-or-lose-it dilemma becomes lose-it-or-use-it for China: the leverage China holds is gradually weakening regardless, so the rational step is to use it while it remains effective. Beijing might do exactly that, but with calibrated, targeted controls rather than a complete embargo.
A coercion that did not begin recently
China’s economic coercion through critical minerals did not begin recently, and it is not something improvised. China’s active use of critical minerals bans can be traced back to the Senkaku incident. The 2010 episode was a critical minerals halt to Japan, after which Beijing laid the foundation for targeted trade countermeasures by introducing a unified act for managing dual-use technology in 2020.
Since then, China has taken critical minerals export controls on different occasions, including the 2023 formal licensing restrictions on gallium, germanium, and graphite, the U.S.-specific ban in December 2024 in response to new U.S. chip controls, the April 2025 restriction on heavy rare-earths and magnets, the first-ever extraterritorial ban in October 2025, and the renewed cut-off to Japan since December 2025, aimed at tightening state control on critical minerals.
It suggested a pattern: each round of control was more legal, more targeted, and wider in reach. The more extensively Beijing leverages its dominance, the more affected states have looked to reduce dependence; therefore, this mitigates China’s ability to exert economic leverage.
Every use teaches the customer to look elsewhere
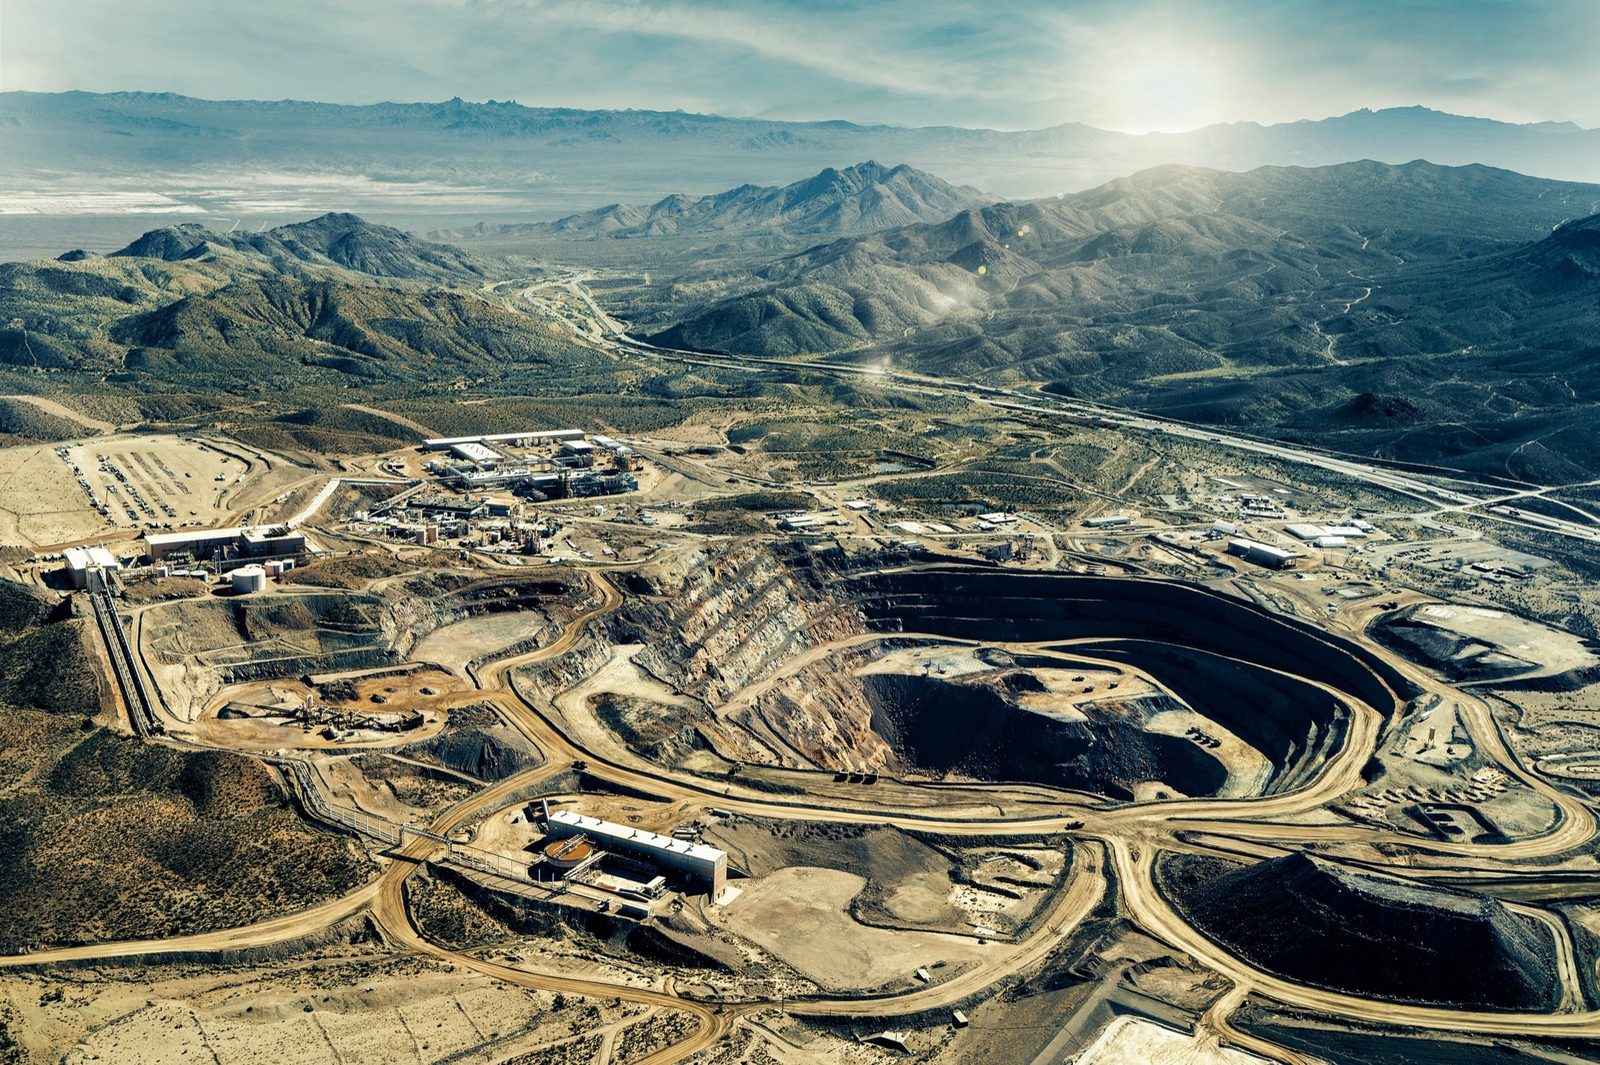
Each episode of China’s restrictions carries a latent cost for Beijing; it teaches its customers to look for alternatives. For instance, after the shock of China’s restrictions, in July 2025, the Pentagon secured $400 million worth of shares in MP Materials, which is the sole company that operates a rare-earth mine in the country. Eventually, the rare-earth minerals are essential for making magnets, which are used in advanced fighters. Additionally, for light and heavy rare-earth oxides, the U.S. has signed a supply deal with Australia’s Lynas, which is the largest rare-earth producer company outside China.
The dependent countries are looking for alternatives; also, the G7, in July 2026, launched a Critical Minerals Alliance for coordination of critical minerals stockpiling and diversification. The world would not have moved at the pace it does now, but China’s coercion has made an optional insurance policy of diversification into a strategic priority, where choices for Beijing become a dilemma.
The dilemma
If China’s repeated use of leverage erodes its credibility, the logical approach for China would be to stop using it. Nevertheless, China may believe that restraint may not protect its strategic position. The threat posed by China’s critical minerals restrictions is known to every state and to manufacturers who depend on China; therefore, no state will avoid hedging merely because China stays quiet. These actions have already compelled the U.S. and other countries to invest in the supply chain, and refineries, magnet plants, and stockpiles will continue operating.
Additionally, holding back also carries a cost for Beijing: if China threatens to use critical minerals as a weapon, though not followed by action, it invites rivals to wonder whether it will be used at all. By showing restraint, China gains little while raising questions about its determination and credibility among other states. If it is using its credibility by holding it back, the logic tilts toward operationalization.
For now, operationalisation pays
But for now, operationalization pays. When Washington imposed strict regulation of its exports in early October 2025, Beijing responded by announcing major regulations regarding rare earths, and within three weeks, President Trump was in Busan agreeing on a truce. The US withdrew a 100 percent tariff threat, and China only postponed the new regulations but did not lift the restrictions employed in April. Once again, rare earths have been shown to be the trump card for Beijing. Behind the trump card, China holds a formidable supply concentration: Beijing accounts for about 60% of global mined production of magnet rare earths, holds nearly 90% of refining capacity, and nearly 95% of permanent magnet production. However, every strategic advantage comes with a cost.
China's strategic advantage has a cost. After the April 2025 controls, Beijing's exports of rare-earth magnets to Washington diminished by 21%. In less than three months, the Pentagon signed a deal with MP Materials. For China, coercion that works may create alarms and push for alternative suppliers, domestic production, and new supply chains. This creates a strategic dilemma for Beijing: if it uses its critical minerals leverage, it may get what it wants today, but other countries will try harder to find alternatives and reduce their dependence on China. Nevertheless, Beijing loses its leverage either way, but it will continue to use this leverage before it becomes ineffective; that is the logic of lose it or use it. However, skeptics will say this overstates how soon that day will arrive.
The counter-argument: diversification is slow
The most significant counterargument is that diversification takes too long, and indeed there is a kernel of truth to the statement. The International Energy Agency has estimated that non-Chinese projects will meet only about a quarter of the demand for refining and less than a fifth for magnets by 2035. Japan has relied on China for 76 percent of its total supply of rare earth metals despite working on the issue for over a decade. However, slow erosion is still erosion, and it is the direction of this trend that drives Beijing's thinking. The leverage still exists, but the time frame for it being relevant is getting narrower and smaller. A narrow window is what pushes a state to act now rather than later. Thus, the significance of January 10th.
Three options on January 10th
When it comes to January 10th, China has three options, but its strategic dilemma favors one approach. The reimposition of the original conditions of the October 2025 regime will exert maximum pressure on its opponents, but strengthen incentives to diversify away from China. A straightforward extension of the pause would raise profound concerns about the reliability of the arrangements. Third, a selective approach should be used. To achieve the goal, it is necessary to resort to certain measures to restrict specific matters, end uses, and companies. In fact, China has already applied this approach. After the truce in Busan, China provided the rest of the world with more rare-earth magnets than in previous years, yet exports to the United States declined.
Lose it or use it
Supply-chain dominance is leverage as long as others depend on it, and subsequently using that leverage ends the dependence. China's deliberate efforts over three decades helped to establish a dominant position in critical minerals, and it may use much of the advantage in the coming years. The question, therefore, is not whether China will use critical minerals leverage, but how quickly it can afford to lose it. In the context of great power competition, critical minerals are now about losing it or using it.
Related: The US–China Truce Is Held Together by Hostages, Not Trust · Why China Will Get What It Wants From Trump

Comments
No comments yet. Be the first.
Comments are closed on this article.